

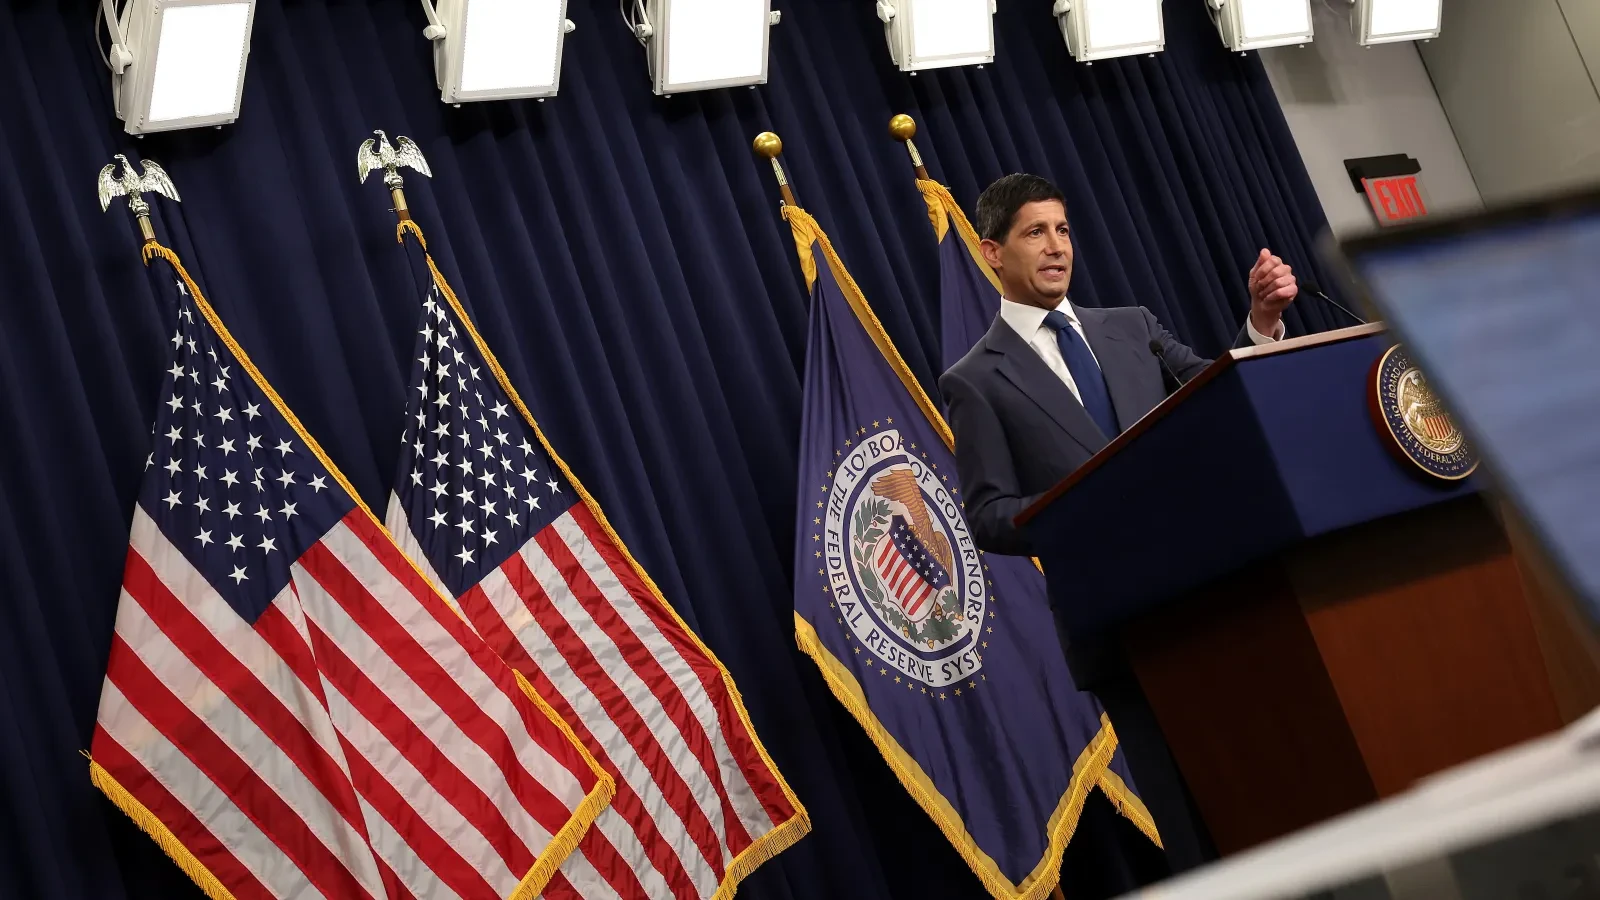
WASHINGTON — In a move that reverberates far beyond Wall Street, the Federal Reserve announced a 25-basis-point increase to its benchmark interest rate, marking the central bank’s first tightening maneuver since 2023. Designed to combat inflation running stubbornly above the Federal Reserve’s stated 2% target, the policy shift immediately sent tremors through the commercial construction and real estate development industries.
For an industry operating on tight margins, supply chain volatility, and heavy capital investments, the rate hike threatens to push marginal construction projects over the financial abyss. While some economists anticipate that the central bank’s aggressive stance could ultimately cool long-term borrowing metrics, real-world operators are bracing for an immediate squeeze on credit, rising material inputs, and a cooling pipeline of new construction starts.
Main Facts: The Anatomy of the Rate Decision
The core mechanism of the Federal Reserve’s recent policy shift is a modest yet impactful 25-basis-point increase in the federal funds rate. While small on paper, the compounding psychological and practical effects on lending markets are swift:
- Immediate Floating-Rate Pressure: Short-term credit lines, construction loans, and revolving debt tied directly to the prime rate will automatically reprice upward, immediately elevating the daily cost of capital for active projects.
- Marginal Project Viability: Commercial real estate development relies heavily on precise financial modeling. With financing costs ticking upward, projects hovering near their minimum profitability thresholds risk falling short of investor hurdles.
- Uneven Sector Vulnerability: The fallout is not distributed equally. While traditional commercial retail, office spaces, and private residential developments are highly sensitive to credit conditions, mega-projects such as semiconductor manufacturing facilities and data centers remain insulated due to corporate cash reserves and heavy government subsidies.
- Persistent Inflationary Headwinds: Even as the central bank attempts to curb monetary expansion, nonresidential construction input costs continue to surge, compounding the pain for developers navigating high interest rates.
Chronology: How the Market Reached This Tipping Point
The intersection of monetary policy and construction economics did not occur in a vacuum. It is the product of years of post-pandemic economic adjustments, supply chain shocks, and shifting central bank priorities:
- The Low-Rate Era (2010s–2020): Construction budgeting norms for the past decade were defined by historically low interest rates. Developers built financial models assuming cheap, accessible capital would remain the status quo.
- The Post-Pandemic Inflation Spike (2021–2022): Global supply chain disruptions sent raw material prices—such as steel, lumber, and concrete—soaring by double-digit percentages year-over-year.
- The Aggressive Tightening Cycle (2022–2023): To combat runaway inflation, the Fed embarked on a historic series of rate hikes. Although pauses followed, inflation remained stubbornly sticky above the 2% benchmark.
- The Resumption of Tightening (Wednesday): Breaking a months-long pause, the Fed enacted a 25-basis-point increase, signaling that the central bank remains deeply concerned about persistent price pressures across the broader economy.
- The Current Crossroads (Present Day): Industry analysts are divided on whether this single hike represents an isolated adjustment or the opening salvo of a new multi-move tightening wave.
Supporting Data: The Squeeze on Capital and Materials
To fully understand the precarious position of commercial contractors, one must examine the hard data governing input costs versus project revenue.
According to historical economic reporting from construction data providers and law firms specializing in infrastructure, nonresidential construction input prices spiked by a dramatic 8.9% year-over-year, with foundational materials registering double-digit surges. Kenneth Roberts, partner and chair of the construction law group at Venable, notes that data reflecting relief in the near term simply does not exist.
“I don’t see any data that suggests that in the next six months, the inflation that the construction industry has experienced in the last year is going to decrease,” Roberts observed. “In fact, I think everybody is stating the opposite. That is, they think that we’re going into even a more inflationary time period.”
Compounding this is the widening gap between material price escalation and contractors’ actual bid prices. Brian Strawberry, chief economist at FMI, highlights the dangerous delta between what materials cost and what clients are willing to pay:
"That squeeze plus costly construction debt is thinning the pipeline of new starts. Fewer deliveries eventually mean tighter vacancies and the next round of rent growth and building. Until then, the planning reality is a cost of capital far above the 2010s."
Official Responses and Industry Perspectives
Industry leaders, economists, and legal experts hold divergent views on how the Fed’s latest action will ripple through the marketplace. While some project immediate pain for general contractors, others look to the bond market for a potential silver lining.
The Bearish View: Immediate Credit Restrictions
Michael Guckes, chief economist at ConstructConnect, warns that the negative impacts will be felt across both planned and ongoing developments.
“In the bigger picture, higher financing costs will weaken the profitability calculations of owners and developers considering new commercial real estate projects,” Guckes explained. “Projects that were on the edge of meeting their profitability goals may now be falling short; such projects will not go to bid.”
Furthermore, Guckes points out the systemic risks for contractors currently on job sites. If floating-rate loans strain a project owner’s cash flow, contractors could experience sudden payment delays. In worst-case scenarios, projects may be paused or entirely abandoned, leaving contractors saddled with immediate expenses and unrecoverable accounts receivable.
The Nuanced View: The Long-Term Treasury Offset
Conversely, Brian Strawberry of FMI suggests that the headline rate hike might inadvertently trigger a stabilizing force for long-term borrowing. Because commercial real estate typically borrows against 10-year Treasury yields rather than the overnight federal funds rate, a decisive Fed action could reassure bond investors that inflation is being contained.
“A hike would immediately raise the cost of floating-rate construction loans, which is real money on projects carrying debt, but the bigger effect is likely lower long-term rates,” Strawberry noted. “A hike that convinces markets the Fed is serious about inflation tends to pull the 10-year [Treasury] down, and that is where construction actually borrows.”
Implications: Sector-by-Sector Fallout and Future Outlook
The broader implications of the Fed’s pivot point toward an uneven, highly stratified construction market over the coming quarters.
1. The High-Risk Sectors: Housing and Private Commercial
Residential housing developments and traditional private commercial real estate (such as strip malls, office parks, and multi-family complexes) are hyper-sensitive to borrowing costs. As mortgage rates and commercial construction loans climb, consumer purchasing power drops, and developer ROI margins evaporate. These sectors are expected to see the sharpest contraction in new project starts.
2. The Sheltered Sectors: Data Centers and Tech Infrastructure
Not all segments of nonresidential construction share this vulnerability. Industrial mega-projects—specifically data centers, electric vehicle manufacturing facilities, and semiconductor fabrication plants—are largely immune to standard credit shifts.
“Much of that spending runs on corporate cash flow and elevated stock values, so borrowing costs barely touch it,” Strawberry explained, noting that massive tech balance sheets and direct government subsidies insulate these builds from traditional financial gravity. “That mix is what keeps total spending from falling as hard as housing.”
3. The Threat of "Rate Waves"
Looking forward, business owners must prepare for the historical precedent of Federal Reserve policy. Historically, the central bank rarely implements a solitary rate adjustment and pauses indefinitely. Instead, monetary tightening tends to arrive in waves.
According to Guckes, modern economic history shows that the Fed favors rapid, sequential adjustments over isolated tweaks. If this historical pattern holds, commercial real estate developers should model their cash flows assuming further increases in the cost of capital before monetary policy eventually pivots toward loosening.
Conclusion
As the construction industry absorbs the shock of the Federal Reserve’s latest benchmark increase, developers and contractors alike must navigate a perilous landscape defined by elevated material costs, tight credit markets, and unpredictable financing waves. While tech-backed mega-projects will steam ahead, the average commercial developer faces a stark reality: projects that barely penciled out yesterday may no longer pencil out at all.
