

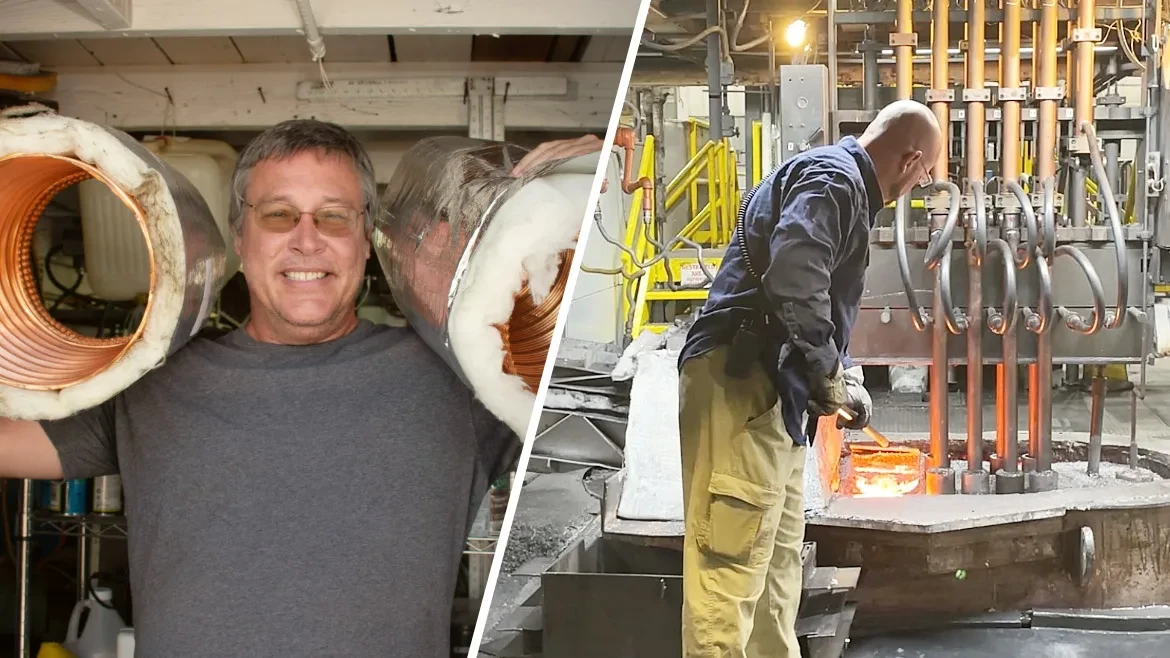
WASHINGTON — America’s ongoing supply chain bottlenecks continue to manifest in the foundational materials required to build, power, and equip the national economy. Among these, copper stands out as one of the most critical structural indicators. Pacing through the electrical grids, heating, ventilation, and air conditioning (HVAC) systems, advanced manufacturing facilities, electrical power infrastructure, and rapidly expanding data centers that power the modern digital age, copper is the invisible architecture of American growth.
Yet, for the contractors, builders, and manufacturers who rely on it daily, the metal has transformed from a standard industrial input into a volatile, high-stakes financial burden.
The cost pressures have been relentless. According to recent federal Producer Price Index (PPI) data, the cost of copper wire and cable surged by 4.2% in a single month. Over the past twelve months, prices have jumped an eye-watering 27.2%. Measured against pre-pandemic baselines in 2020, copper wire and cable prices have skyrocketed by an astronomical 104.9%.
However, this relentless upward trajectory hit a sudden roadblock when global copper prices dropped sharply following indications that the White House was reconsidering prospective tariffs on refined copper imports.
While a sudden decline in commodity prices might sound like immediate relief for contractors and builders bogged down by years of high inflation, the economic reality on the ground is far more complex. A policy debate in Washington can trigger an overnight swing in exchange-traded metal prices, but it cannot manufacture new physical copper, build a processing smelter, or instantly restock depleted distributor warehouses.
Chronology of a Volatile Week
To understand the current disconnect between Wall Street commodities trading and Main Street construction sites, one must examine the rapid series of events that sent shockwaves through the metals market in September.
The drama began as global copper inventories tightened significantly, driven by flagging mine production abroad and rising anticipation that the Trump administration would extend sweeping import duties to refined copper products. In response to the looming threat of protectionist trade policies, traders, institutional buyers, and industrial conglomerates aggressively rushed to build up domestic U.S. inventories. Warehouses across the country absorbed massive quantities of foreign metal ahead of potential tariff implementation dates, creating a localized supply bottleneck.
This speculative frenzy pushed three-month copper futures on the London Metal Exchange (LME) to historic record highs. U.S. domestic copper futures similarly surged, pricing in a worst-case scenario for import costs.
The tide turned abruptly mid-week. According to reports from Reuters, the White House signaled that it had not yet made a definitive, final decision regarding tariffs on refined copper. Administration officials found themselves carefully weighing the long-term strategic benefits of bolstering domestic mining against the immediate, painful economic consequences of driving up costs for American manufacturers and construction firms.
The market’s reaction was instantaneous. Three-month copper on the London Metal Exchange plunged 3.1% after touching record highs earlier in the same trading session. U.S. copper futures registered parallel, precipitous declines.
Yet, for project managers and trade contractors, the dramatic dip on trading floors did not translate to cheaper materials. The proposed tariffs have not been formally imposed, nor have they been withdrawn or definitively rejected. Furthermore, a momentary drop in exchange-traded benchmark copper does not translate to an equivalent, immediate price drop for finished wire, complex electrical equipment, or specialized copper-intensive components tomorrow.
Supporting Data: The Downstream Toll on Construction
The disconnect between paper futures and physical inventory underscores how deeply price inflation has already penetrated the supply chain.
+-------------------------------------------------------+
|          COPPER INFLATION TIMELINE (PPI DATA)         |
+-------------------------------------------------------+
| Baseline (2020)       | 100.0% (Index Reference)      |
| 1-Year Trailing       | +27.2% Increase               |
| August Single-Month   | +4.2% Surge                   |
| Total Surge Since '20 | +104.9% Cumulative Inflation  |
+-------------------------------------------------------+
This cumulative inflation is exacting a heavy toll on the broader construction sector. Ken Simonson, chief economist at the Associated General Contractors of America (AGC), pointed out the severe economic squeeze facing modern builders.
"Construction firms are being squeezed by tariff- and war-induced materials cost increases, even as they boost wages to attract personnel," Simonson stated, highlighting the dual pressures of soaring input costs and a persistent skilled labor shortage.
The financial strain is no longer theoretical—it is actively halting commercial and residential development. A recent comprehensive AGC survey revealed that 55% of respondent construction firms have had projects either outright canceled, indefinitely postponed, or significantly scaled back over the preceding six months. Among those experiencing disruptions, one-third directly attributed their troubles to escalating materials costs.
Jeffrey D. Shoaf, CEO of the AGC, elaborated on the untenable position in which contractors currently find themselves.
"As firms pay more to address labor shortages and materials prices continue to climb, they are caught between pricing themselves out of the market or performing work at a loss," Shoaf warned.
Official Responses and Strategic Perspectives
The federal government’s use of tariffs is designed to achieve a clear, strategic objective: incentivize domestic metal production, reduce America’s historical reliance on foreign supply chains, and build long-term industrial self-sufficiency. However, the copper market exposes a glaring timing problem inherent in this protectionist strategy.
The United States currently imports roughly half of all the copper it consumes annually. Compounding this vulnerability, the nation boasts only two operating primary copper smelters. Constructing new mining ventures, building multi-billion-dollar smelting facilities, and establishing advanced refining capacities cannot happen overnight; such capital-intensive projects require years, if not decades, of regulatory approval, financial investment, and engineering.
Jason Munoz, managing director at FMI Capital Advisors, cautions against misinterpreting the recent market selloff as a permanent resolution to the crisis.
"I would say that the market is looking at it as a potential delay or deferment, not an outright cancellation, and is still pricing in some risk of tariffs ultimately being imposed post-midterms," Munoz explained.
Munoz also emphasized a crucial distinction between the new trade policies under consideration and those already legally codified. Tariffs enacted in 2025 on semi-finished copper products remain fully in effect. These existing measures levy a steep 50% duty on the copper content of covered semi-finished goods and derivative products. More importantly, the underlying global supply and demand imbalances have not disappeared.
"Global demand is still outstripping supply, especially in international markets given the rush to import copper into the U.S. in advance of tariffs," Munoz added.
The Supercycle Debate
Industry analysts remain sharply divided on the long-term trajectory of the metal. Investment firms like Sprott argue that critical energy transition materials, including copper, have entered a fundamentally new commodity supercycle, driven by structural demand from electrification and systemic supply constraints.
Conversely, StoneX senior metals analyst Natalie Scott-Gray views the market through the lens of "structural tightening." Scott-Gray points to declining ore grades at aging operating mines, systemic underinvestment in new greenfield supply projects, and a projected structural market deficit.
Regardless of which analytical framework proves accurate, contractors face the same sobering reality: adding new global supply is becoming exponentially more difficult precisely as demand from data centers, power grids, and advanced manufacturing accelerates.
Broader Economic Implications for Trade Contractors
The federal government has previously confronted this exact policy tradeoff elsewhere within the industrial and residential supply chains.
In June, the administration shifted certain residential HVAC systems and underlying components into a temporarily reduced 15% tariff category. Officials cited the critical role these climate control systems play in productive U.S. economic activity and acknowledged the acute cost pressures facing the industries utilizing them. Select items of industrial machinery received similarly modified regulatory treatment.
This ongoing policy tension is acutely visible in the copper sector. While tariffs can theoretically improve the long-term economics of domestic mining, smelting, and refining, they simultaneously drive up the cost of an essential manufacturing input before alternative domestic capacity has been brought online. Encouraging domestic production is a vital long-term policy objective, but contractors, builders, and manufacturers require physical materials today to keep their businesses operational.
Navigating a Moving Target
For HVAC contractors, electricians, and general tradespeople, copper pricing volatility is merely one component of a broader, multi-front cost crisis. Labor rates, logistics and transportation charges, chemical refrigerants, structural steel, and primary aluminum are all experiencing simultaneous price fluctuations.
Contractors are routinely forced to bid and lock in firm fixed prices for customers months before heavy equipment is officially ordered or physical construction begins.
Steve Howard, founder of ACT Group Inc., emphasized that modern trade contractors must completely overhaul their financial planning methodologies to survive this era of macro-economic unpredictability.
"A pricing for profit process allows you to know when and how much to adjust pricing during a rapidly changing economy," Howard noted, arguing that businesses must adopt systematic pricing formulas rather than reacting emotionally to every incremental market spike.
Anirban Basu, chief economist for the Associated Builders and Contractors (ABC), has issued similar warnings regarding aggregate construction input costs. While periodic monthly reports occasionally show dips in headline input costs—often driven by temporary drops in fossil fuels—Basu consistently cautions against celebrating false dawns. He points to persistent, steep structural increases in tariff-impacted commodities like iron, steel, and copper as proof that underlying cost pressures remain severe.
What Contractors Should Watch For
Ultimately, the recent pullback in copper futures serves as an important lesson in market mechanics. A temporary monthly decline in a single exchange-traded commodity does not mean the broader construction cost crisis has broken. Neither does a single erratic week of falling copper prices on Wall Street.
For contractors planning their fiscal futures, the true operational signals to watch are downstream:
- Do the recent commodity price drops persist long enough to permanently lower wholesale wire, cable, and equipment distributor quotes?
- Are major suppliers beginning to extend price validity windows, or are they keeping tight, short-term expiration dates on quotes?
Until physical supply catches up with structural global demand, the American construction economy will remain caught in the crosshairs of the great copper squeeze.
