

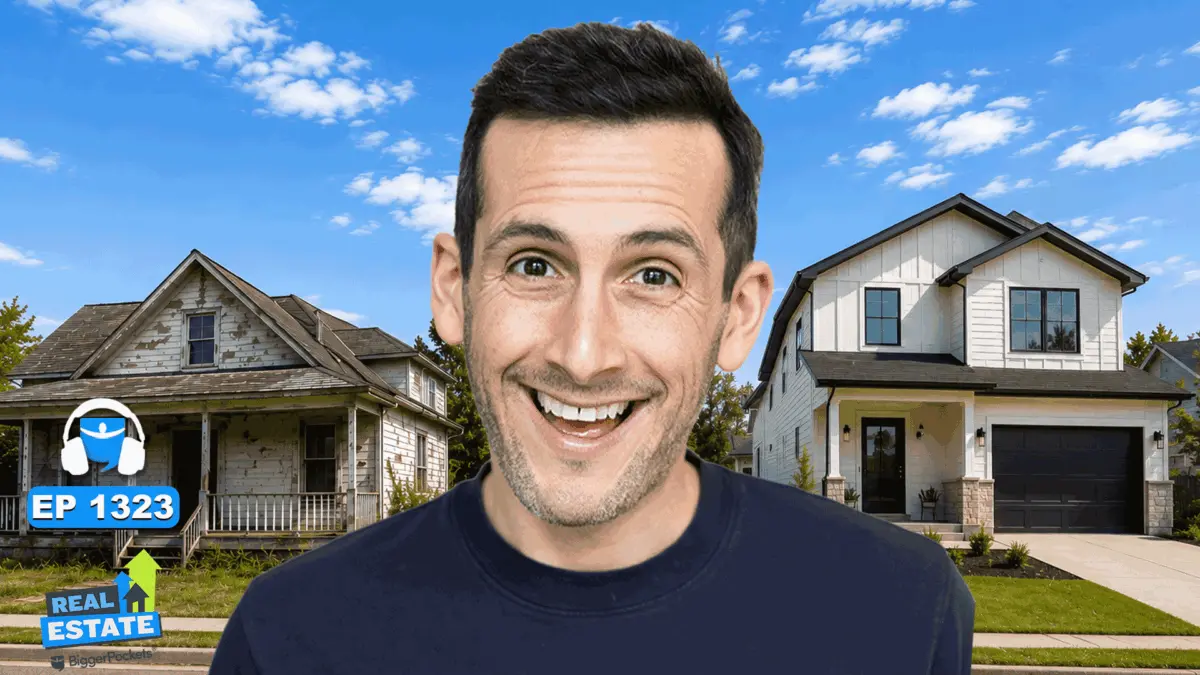
For over a decade, the playbook for residential real estate investors was practically set in stone. If you wanted to build wealth, achieve forced appreciation, and rapidly scale your portfolio, you looked for a distressed, uninspired fixer-upper. You bought it at a discount, renovated it to increase its market value, rented it out, and refinanced your capital out to repeat the cycle all over again. This strategy—famously known as the BRRRR method (Buy, Rehab, Rent, Refinance, Repeat)—was the undisputed king of real estate investing strategies.
However, the macroeconomic landscape of 2026 has introduced market conditions that challenge traditional wisdom. Major homebuilders are currently sitting on mountains of unsold inventory, forcing them to slash prices and roll out aggressive buyer incentives just to clear their books. Meanwhile, newly constructed homes are, on average, trading for less than existing resale properties—a rare market anomaly.
To determine whether the classic fixer-upper still reigns supreme or if new construction has stolen the crown, real estate expert and podcast host Dave Meyer put two real-world deals in the exact same market—Sherman, Texas—head-to-head. The resulting analysis reveals striking trade-offs in cash flow, equity growth, and long-term portfolio strategy.
Main Facts: The 2026 Market Shift
The debate between value-add properties and new construction centers around a fundamental shift in how builders and individual sellers operate.
- The Builder’s Dilemma: Unlike individual homeowners who can simply pull their property off the market if they dislike current pricing, commercial homebuilders operate on a strict inventory-turnover model. If they fail to move built properties, they incur continuous holding costs. To prevent this, builders are heavily discounting homes and offering aggressive incentives, such as mortgage rate buydowns (dropping investor rates to around 4.5%), closing cost credits, and upgraded fixtures.
- The Pricing Anomaly: According to data from the National Association of Home Builders (NAHB), the median price for a newly built home has dropped below the median price of an existing home in many parts of the country—a stark reversal of historical pricing trends.
- The Geographic Focus: To run an accurate comparison, Meyer targeted Sherman, Texas—a rapidly growing small city north of Dallas. Sherman benefits immensely from massive economic catalysts, including a $60 billion chip-manufacturing investment by Texas Instruments that is driving high-paying jobs and surging housing demand. Despite these tailwinds, home prices in the area remain roughly half the national average.
Chronology of the Analysis: Two Deals Head-to-Head
To provide a true apples-to-apples comparison, Meyer analyzed two single-family properties located in the same market of Sherman, Texas, evaluating both through financial calculators to measure cash-on-cash return, cash flow, and compound annual growth rate (CAGR).
Property A: The New Construction Deal (Lennar Home)
- Purchase Price: $243,000 (asking price)
- Specifications: 4 bedrooms, 2 bathrooms, 1,700 square feet, single-story ranch with a two-car garage.
- Financing & Incentives: Utilizing a 25% down payment ($60,750), the builder’s promotional financing allowed for a 4.5% mortgage rate (significantly lower than the standard 7% investor rate) and zero closing costs ($3,500 saved).
- Projected Rent: $2,000 per month.
- Operating Expenses: Texas property taxes hit hard at 2.2% ($5,346 annually), paired with $1,280 in insurance. Because the home is brand new, capital expenditures and maintenance reserves were kept conservatively low at 5% combined, alongside an 8% property management fee.
- Initial Financial Outcome: Unadjusted, the property yielded a modest 1% cash-on-cash return. However, after successfully negotiating the 4.5% rate buydown and eliminating closing costs, the cash-on-cash return climbed to 3.25%, generating positive, low-stress cash flow backed by builder warranties.
Property B: The BRRRR Fixer-Upper Deal
- Purchase Price: $160,000
- Specifications: 4 bedrooms, 3 bathrooms, 1,700 square feet, built in 1961 on an 8,000-square-foot lot with a one-car garage.
- Rehab Budget: $35,000 (including a safety buffer for unexpected structural surprises), targeting an After Repair Value (ARV) of $260,000 to $270,000.
- Financing: Purchased with a 25% down payment at a standard investor interest rate of 7%.
- Projected Rent: $2,050 per month, slightly higher due to its more mature, walkable neighborhood location near downtown Sherman.
- Operating Expenses: Property taxes of roughly $4,800 annually, insurance at $1,200, higher maintenance reserves (5%), and higher capital expenditure reserves (8%) due to the home’s 1960s origin.
- Initial Financial Outcome: Right out of the gate, the property generated $218 a month in cash flow, translating to a 3.3% cash-on-cash return—roughly equivalent to the optimized new construction deal.
Supporting Data: Cash Flow vs. Equity Growth
While the cash-on-cash returns for both properties initially appeared neck-and-neck (around 3.25% to 3.3%), a deeper dive into the numbers revealed where each strategy truly excels.
| Metric | New Construction (Lennar) | BRRRR Fixer-Upper |
|---|---|---|
| Initial Cash-on-Cash Return | ~3.25% (Optimized with rate buydown) | ~3.3% |
| Monthly Cash Flow | ~$53 to $200 (Depending on price negotiation) | $218 |
| Compound Annual Growth Rate (CAGR) | ~10% | ~17% |
| Capital Required Upfront | Higher purchase price ($243k) | Lower purchase ($160k) + Rehab ($35k) |
| Maintenance & CapEx Risk | Minimal (Covered by warranties; low initial repairs) | High (Older systems, plumbing, electrical, and roof risks) |
The most glaring data discrepancy lies in the Compound Annual Growth Rate (CAGR). While the new construction property tracked a healthy 10% annual growth rate (comparable to or better than the stock market), the BRRRR property achieved an impressive 17% CAGR.
This spike was not driven purely by cash flow, but by forced appreciation. By investing $35,000 into renovations, the investor successfully drove up the property’s equity by nearly $100,000.
Official Responses and Expert Insights
Industry analysts and real estate veterans note that while the math for new construction has become exceptionally attractive in 2026, psychological and structural barriers remain.
Dave Meyer emphasizes that the modern viability of new construction rests almost entirely on seller concessions and rate buydowns. "If you cannot negotiate that 4.5% mortgage rate instead of the standard 7%, the numbers on new construction simply do not work," Meyer notes. "The rate buydown takes a deal that would traditionally have negative cash flow and turns it into a performing asset."
At the same time, veteran investors caution that builders will fiercely protect their base purchase prices to avoid lowering comparable sales values (comps) for future phases of their developments. Consequently, investors must negotiate creatively—focusing first on rate buydowns, second on closing cost credits, and third on extended warranties or upgraded fixtures rather than demanding direct price cuts.
Implications: Which Strategy Should You Choose in 2026?
Ultimately, the choice between buying new construction and executing a BRRRR strategy depends heavily on an investor’s personal capital, available time, and career phase. Market experts categorize investors into distinct groups to guide this decision:
1. The Aggressive Scaler (Choose BRRRR)
If you are early in your real estate investing career, possess limited capital, and want to achieve financial freedom within 7 to 10 years, the BRRRR method remains unmatched. The ability to recycle your capital by pulling your initial investment back out through a cash-out refinance allows you to acquire property after property. The sweat equity and forced appreciation generated by renovations provide a compounding growth engine that new construction simply cannot replicate.
2. The Full-Time Professional with a Long Horizon (Choose New Construction)
If you work a demanding full-time job and view real estate as a 15- to 20-year wealth-building vehicle, new construction is a compelling alternative. With zero maintenance headaches, builder warranties, and high renter demand driven by modern amenities, new construction offers predictability. If your income allows you to comfortably purchase a turnkey property every few years without relying on rapid refinancing cycles, you can build a stable, low-stress portfolio.
3. The Cash-Rich Investor or "Harvest Phase" Retiree (Choose New Construction)
Investors who already possess significant liquidity—or those currently in the "harvest phase" of their investing lifecycle who want to downsize and simplify their management burden—benefit greatly from new construction. Trading the active management of older, distressed properties for predictable, tax-advantaged cash flow from brand-new assets makes retirement management significantly easier.
Conclusion
The real estate market of 2026 has blurred the lines between traditional value-add investing and turnkey buying. While the BRRRR method remains the undisputed king of portfolio scaling, unprecedented builder concessions have elevated new construction from an afterthought into a viable, high-performing strategy for the modern investor. As always in real estate, success ultimately comes down to running the math and aligning the strategy with your personal goals.
