

By Energy & Policy Desk
Published June/September 2026
Main Facts
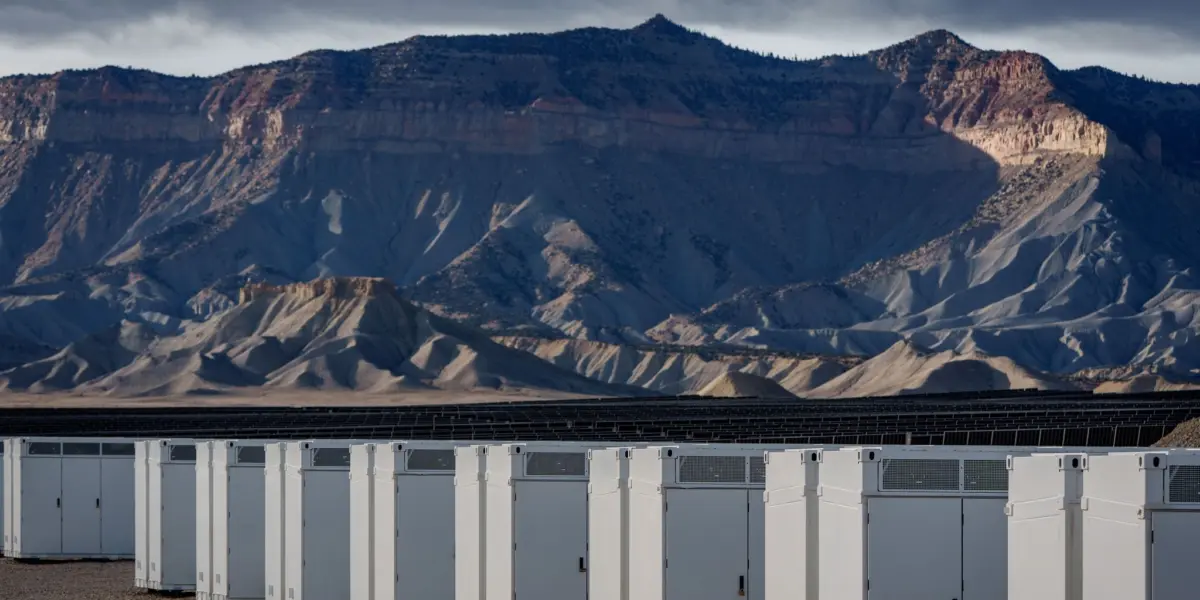
The United States clean energy sector achieved a monumental milestone in the second quarter of 2026, crossing a threshold that cements solar power as a primary pillar of the nation’s power grid. According to the latest US Solar Market Insight report—jointly published by the Solar Energy Industries Association (SEIA) and energy research firm Wood Mackenzie—the cumulative US solar fleet has reached enough installed capacity to generate clean electricity equivalent to the consumption of more than 50 million homes.
To put this into perspective, this output represents more than one-third of all residential households in the United States. While this metric is an industry calculation converting total fleet generation capacity rather than a direct household feed, it underscores the staggering scale and speed at which photovoltaic (PV) technology has integrated into the American energy landscape.
The catalyst for this landmark achievement was an exceptionally robust Q2 2026, during which the industry installed an impressive 11.4 gigawatts direct current (GWdc) of new capacity. This figure represents a dramatic 45% surge year-over-year and a 43% leap compared to the first quarter of 2026. Combined with battery storage, solar and storage technologies together accounted for an overwhelming 70% of all new US power generation capacity added in the first half of the year.
Despite an evolving political landscape marked by the rolling back of federal clean energy incentives under the Trump administration and congressional Republicans, market demand—particularly across conservative-leaning states—has not only sustained the sector but propelled it to historic new heights.
Chronology
To understand how the US solar sector reached this milestone in mid-2026, it is helpful to look at the recent timeline of regulatory shifts, industry rushes, and market adjustments:
- December 31, 2025: The federal Residential Clean Energy Credit, which historically covered 30% of the installation costs for qualifying home solar and battery systems, officially expired for systems placed in service after this date. This created a late-2025 rush for residential installations followed by a cooling-off period in early 2026.
- Q1 2026: Despite the expiration of residential tax credits, utility-scale developers began accelerating project pipelines to adapt to shifting federal policy landscapes and looming regulatory milestones.
- July 2026: A critical safe harbor deadline for federal utility-scale tax credits loomed large over the energy sector. Developers rushed to break ground and secure equipment, driving unprecedented momentum into the second quarter.
- Q2 2026: The US solar industry officially installed 11.4 GWdc of new capacity. This massive quarter pushed the nation’s cumulative solar output past the 50-million-home equivalent milestone, fueled primarily by utility-scale utility projects racing the July deadline.
- Late 2026 and Beyond: The industry transitions into a post-Investment Tax Credit (ITC) environment. While utility-scale solar maintains a massive multi-year backlog, analysts project a brief stabilization period for rooftop solar before a projected rebound in 2027.
Supporting Data and Market Analysis
The numbers driving the Q2 2026 report reveal a market that is evolving rapidly, driven heavily by utility-scale momentum while navigating headwinds in the residential sector.
Utility-Scale Dominance
Large-scale solar farms were the undisputed engine of Q2 growth. Utility-scale projects accounted for 9.6 GWdc of the quarter’s 11.4 GWdc total—a massive 61% increase year-over-year. Developers raced aggressively to lock in projects ahead of the pivotal July 2026 safe harbor deadline for federal tax incentives.
Market analysts at Wood Mackenzie project that this pipeline will remain robust. The firm estimates that the US will continue to add approximately 44 GWdc of solar annually through 2031, a trajectory that will nearly double the country’s total operating solar capacity over the next five years.
The Red State Paradox
Perhaps the most striking narrative emerging from the 2026 data is the geographic distribution of new solar installations. Despite the federal administration’s hostile stance toward renewable energy subsidies, market forces and local economic realities have driven massive adoption in conservative heartlands.
States that voted for Donald Trump in the 2024 presidential election accounted for a staggering 71% of all solar capacity installed in the first half of 2026. Furthermore, eight out of the top ten leading states for new solar installations are traditionally classified as "red states." This data highlights a powerful reality: cheap land, abundant sunshine, and the economic imperative for affordable electricity have decoupled solar adoption from federal partisan politics.
Rooftop Solar Headwinds
In stark contrast to the utility sector, the residential rooftop market faced significant turbulence in early 2026. The expiration of the federal Residential Clean Energy Credit at the close of 2025 created immediate friction for homeowners looking to install panels or home batteries.
However, industry analysts remain optimistic about the long-term outlook for distributed generation. Wood Mackenzie forecasts that residential solar and storage will resume positive growth by 2027, driven by persistent consumer demand to lower rising utility bills and secure reliable backup power during extreme weather events and grid outages.
Official Responses and Stakeholder Perspectives
Industry leaders and market analysts have offered vital context on what these milestones mean for the broader US economy and power grid.
Tim Pawlenty, CEO of the Solar Energy Industries Association (SEIA), emphasized the sheer scale that clean energy has achieved:
"Solar and storage have grown to a scale most Americans have yet to fully realize, and we simply can’t meet America’s growing energy needs without these technologies."
With electricity demand climbing steeply nationwide—driven by data center expansions, artificial intelligence infrastructure, and the electrification of transportation—Pawlenty’s remarks underscore why utilities and grid operators are leaning heavily on solar and storage solutions that can be deployed quickly and cost-effectively.
On the analytical side, Caitlin Connelly, senior analyst at Wood Mackenzie, highlighted the operational and regulatory hurdles the industry must navigate in the quarters ahead:
"However, permitting and the post-ITC transition remain significant headwinds."
While project pipelines are robust, developers continue to face bottlenecks related to transmission interconnection queues, localized zoning opposition, and navigating the shifting federal tax credit framework. Resolving these transmission and permitting blockades will be crucial to meeting Wood Mackenzie’s projection of 44 GWdc added annually through the next decade.
Implications for the Future
The implications of the Q2 2026 solar report extend far beyond milestone figures and clean energy statistics. They point to a fundamental reshaping of the American power grid.
- Meeting Soaring Power Demand: As power demand scales upward at rates not seen in decades, traditional fossil fuel plants cannot be built fast enough to keep pace. Solar and battery storage—making up 70% of new capacity added in the first half of 2026—offer the only viable combination of speed, scale, and low cost capable of filling the gap.
- Economic Resilience Over Politics: The heavy concentration of solar projects in red states demonstrates that energy infrastructure development is increasingly driven by economic viability rather than federal mandates. Local tax revenues, job creation in rural counties, and cheap generation costs have turned conservative lawmakers and landowners into pragmatic supporters of renewable energy buildouts.
- Grid Reliability and Storage Integration: The pairing of solar with utility-scale battery storage is no longer an experimental concept; it is the baseline standard for new energy projects. This integration addresses the intermittency challenges of solar generation, ensuring that clean power can be dispatched during peak evening hours when energy demand spikes.
- Consumer Adaptation: Although residential solar faces a transitional valley following the expiration of the 30% tax credit, the fundamental economic pressures driving homeowners toward solar—namely, persistently high retail electricity rates and growing anxiety over grid reliability—remain completely intact. As installation financing adapts to the post-credit era, consumer adoption is widely expected to rebound.
As the United States pushes toward the latter half of the decade, the Q2 2026 data proves that the clean energy transition has crossed a point of no return. Driven by utility-scale momentum, corporate demand, and grassroots economic appeal across the political spectrum, American solar is no longer an alternative energy source—it is the backbone of the modern grid.
